
Every month, small business owners pay expenses such as software subscriptions, vehicle costs, repairs, and other business-related bills. But what if the way you pay those expenses could help gradually convert your non-deductible mortgage debt into tax-deductible debt?
This is the idea behind cash damming, a mortgage optimization strategy that may help certain business owners and rental property owners improve their debt structure over time.
If you operate an unincorporated business or personally own a rental property, here’s how the strategy can work.
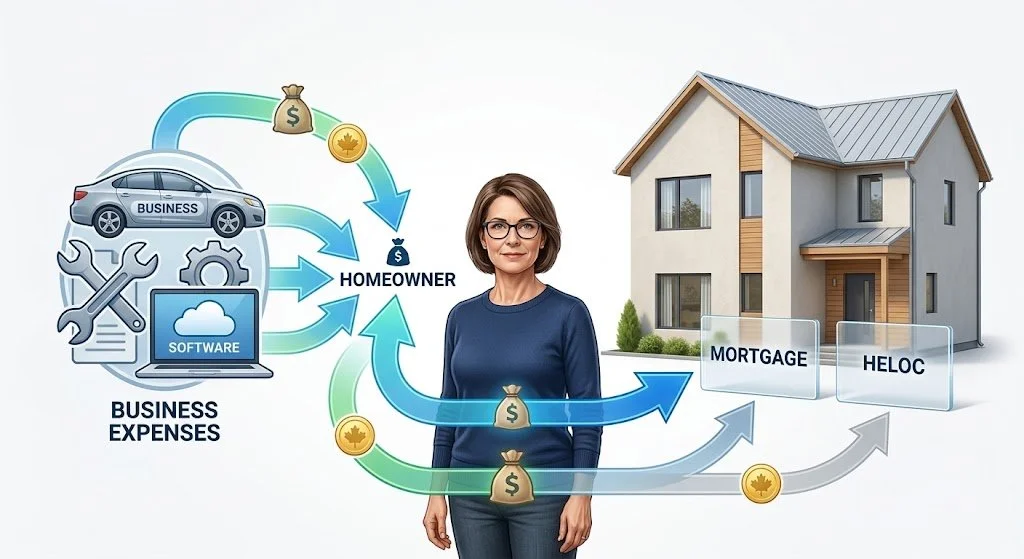
What Is Cash Damming?
Cash damming is a strategy that uses borrowed money to pay eligible business or rental expenses while redirecting the income that would have covered those expenses toward your personal mortgage.
The goal is to gradually replace personal mortgage debt with debt used to earn business or rental income.
You may have heard of this strategy in the context of rental properties, but it can also apply to certain small business owners.
How Cash Damming Works
Let’s say you have a mortgage connected to a HELOC (Home Equity Line of Credit) and $3,000 in eligible business or rental expenses each month.
Instead of using your available cash to pay those expenses, you borrow $3,000 from the HELOC to cover them.
You then use the $3,000 of business or rental income that would have paid those expenses to make an additional payment against your mortgage, subject to your lender’s prepayment privileges.
After One Year
If you repeat this process every month for 12 months:
Your mortgage could be $36,000 lower.
Your HELOC could be $36,000 higher.
The HELOC funds could be traced to eligible business or rental expenses.
Your total debt has not necessarily changed. Instead, $36,000 has moved from personal mortgage debt toward debt used to earn income.
Repeat the process each year, and the conversion can continue.
Why Can the HELOC Interest Be Tax Deductible?
The tax treatment depends on how the borrowed money is used.
Under paragraph 20(1)(c) of the Income Tax Act, interest may generally be deductible when borrowed money is used for the purpose of earning income from a business or property, provided the applicable requirements are met.
That means the interest on the HELOC may be deductible when the borrowed funds are used for eligible business or rental expenses.
However, simply having a HELOC connected to your mortgage does not automatically make the interest tax deductible. The use of the borrowed funds and the ability to trace them to eligible expenses matter.
Cash damming tends to work most cleanly for sole proprietors, certain partners, and individuals who personally own rental properties. The rules can be different for incorporated businesses, so the strategy should be reviewed based on your specific circumstances.
Why Mortgage Renewal Is a Good Time to Explore This Strategy
Mortgage renewal can be an efficient time to explore a readvanceable mortgage structure.
A readvanceable mortgage typically combines a mortgage with a HELOC that can become available as you pay down the mortgage, subject to the lender’s terms and approval.
At renewal, you may have an opportunity to restructure your mortgage without paying a penalty to break your existing mortgage early.
This can be a good time to explore whether the right structure could support your cash damming strategy.
Don’t Miss Your Renewal Window
If you are a small business owner or rental property owner, it is worth exploring your mortgage options before signing your renewal.
Sometimes breaking a newly renewed mortgage can still make financial sense, but paying a penalty on a mortgage you just renewed can be frustrating and expensive.
Whether you are looking for help with the mortgage or tax side of the strategy, I can help determine whether cash damming fits your situation, work with your existing lender, or help you explore a mortgage structure that supports your goals.
Ready to explore your mortgage options?
Book a financing and mortgage strategy call before signing your renewal.
General information only. Cash damming and mortgage interest deductibility depend on your specific circumstances. Consult a qualified tax professional to determine whether the strategy is appropriate for you.
